Car Loan Finance Online Car Loan Repayment Calculator
Calculate car loan repayments with our Car Loan Repayment Calculator. View detailed amortization charts to compare terms, track interest, and plan your budget with confidence.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Car Loan Details:
Important!
Car Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Loan Amortisation Calculator
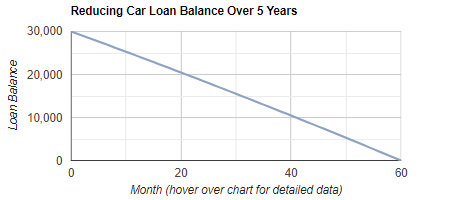
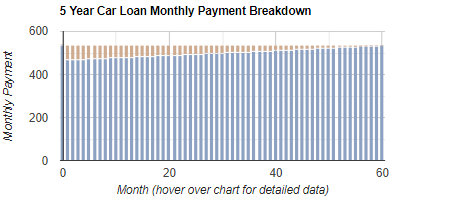
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Car Loan Repayment Calculator
Our Car Loan Repayment Calculator helps you estimate repayments for an Australian car loan and see how your balance, interest and principal change over time. It is important because small changes to the loan amount, term or interest rate can materially affect your monthly budget and the total interest you pay. The amortisation charts make it easier to compare scenarios and choose a structure you can afford with confidence.
General information only: This calculator provides an estimate and does not take into account your objectives, financial situation or needs. Results are indicative and your actual interest rate and repayments will depend on the lender, your credit profile and the final loan contract (including fees and conditions).
How to complete each section for the best result:
1. Purchase Price
Enter the vehicle purchase price as a whole number (no decimals or commas). If you plan to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts here so the estimate better reflects your likely loan size.
2. Deposit or Trade-in Value
Enter your cash deposit and/or trade-in value as a whole number. A higher deposit reduces the amount financed and usually lowers repayments and total interest.
3. Term of Loan (Years)
Select the number of years you want to repay the loan over. Shorter terms usually mean higher repayments but lower total interest. Longer terms can reduce monthly repayments but typically increase total interest paid.
4. Interest Rate (% per annum)
Select an interest rate to simulate. If you have a quote, choose the closest rate. If comparing options, run multiple calculations to see the impact of different rates.
5. Calculate
Click calculate to generate your results and charts.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability, leaving buffer for running costs and rate changes.
2. Amortisation charts: One chart shows the loan balance reducing over time; the other shows how early repayments are often interest-heavy and gradually shift toward principal repayment.
3. Comparison planning: Re-run the calculator with different terms, deposits and rates to identify a repayment level and total interest outcome that suits your budget.
Applying for a car loan in Australia usually involves checking affordability, preparing documents, submitting an application, lender assessment, conditional approval, vehicle checks, contract signing and settlement. This guide explains the typical steps and what can affect the outcome. - read more
In the world of personal finance, a credit score plays a pivotal role in determining your borrowing power. But what exactly is a credit score? Simply put, it's a numerical representation of your creditworthiness, based on an analysis of your credit files. This score helps lenders assess the risk of lending you money or extending credit. - read more
Welcome to a beginner's guide to saving for your first car! Buying a car for the first time is an exciting journey, filled with anticipation and, sometimes, a bit of anxiety. Rest assured, you are not alone on this path. Many Australians have taken these steps before you, and with the right strategies, you can turn this experience into a rewarding achievement. - read more
Business vehicle finance can affect cash flow, GST, deductions, depreciation, private use records and fringe benefits tax. This guide explains the general tax concepts Australian small business owners and sole traders should understand before choosing a business car loan or vehicle finance structure. - read more
ASIC’s latest review of mortgage broker conduct has put a spotlight on how loan recommendations are explained, documented and challenged when a cheaper option is available. Although the review focused on home loan brokers, the practical lesson is broader: borrowers should understand not only the advertised rate, but also why a particular loan structure, lender or feature is being presented as suitable. - read more
Australia’s electric truck conversation has shifted from vehicle availability alone to the practical question of where, when and how commercial vehicles will charge. Ampol’s October 2026 activity has made that shift clearer, with the company announcing a proposed acquisition of Evie Networks and a separate memorandum of understanding with Foton Mobility Distribution to explore charging solutions for electric commercial vehicles. - read more
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
Australia’s motorcycle market is ahead of last year after the first nine months of 2026, but the latest FCAI-audited figures point to a recovery driven mainly by off-road demand rather than a uniform lift across every type of bike. For riders thinking about motorbike finance, that distinction matters because the practical costs attached to a trail bike, junior motorcycle, scooter or road machine can look very different once purchase price, transport, gear, insurance and maintenance are considered together. - read more